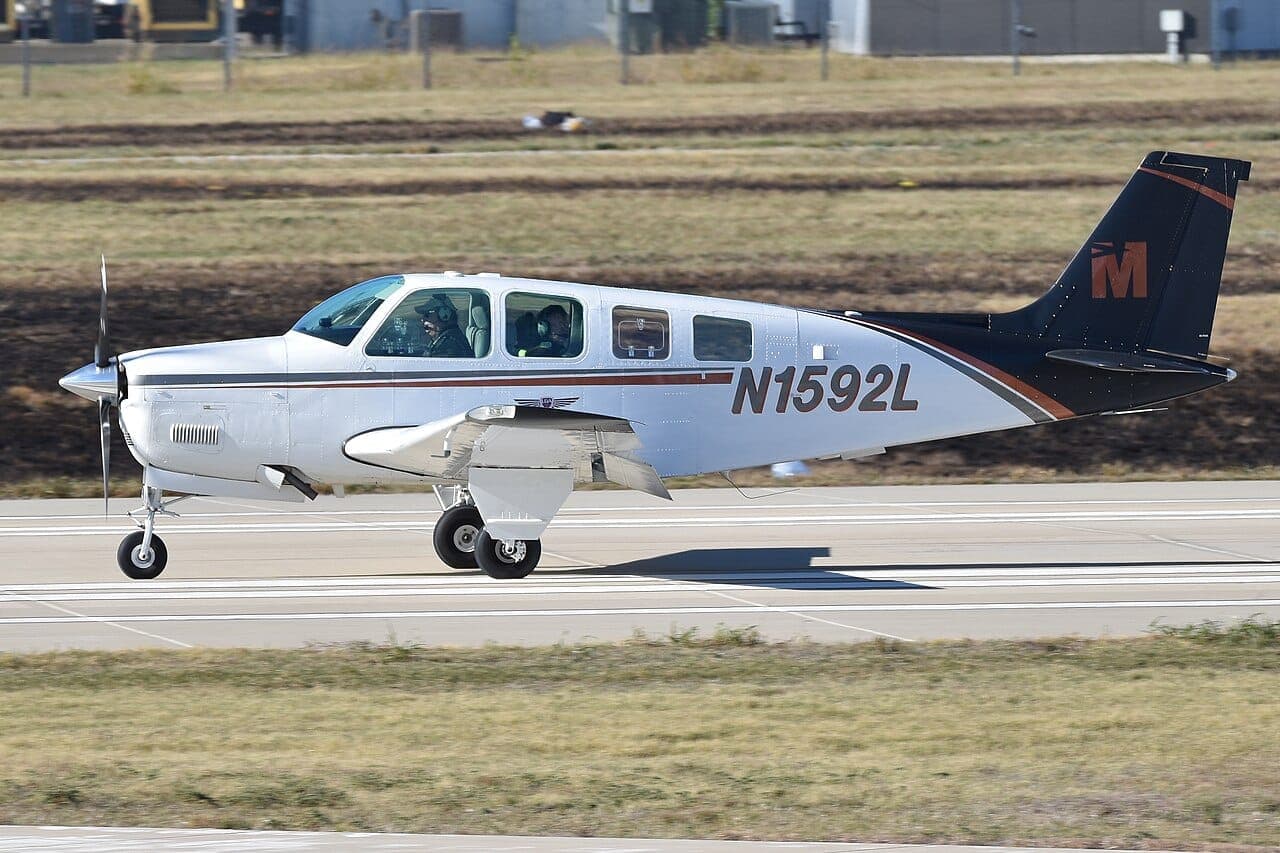
A gear-up landing in a retractable single can result in tens of thousands of dollars in damage even when nobody is injured. A propeller strike may require extensive engine inspections, propeller repairs and replacement of damaged belly panels, gear doors or other components. Lycoming's current Service Bulletin 533D recommends detailed inspection procedures following qualifying propeller strikes, while the legal requirements depend on applicable airworthiness directives, maintenance requirements and the aircraft's operation. That single claim type is the reason insurance for a retractable or high-performance single is quoted so differently from insurance for the Skyhawk you trained in — and the reason a 240-hour private pilot gets told "no market" on an A36 Bonanza.
Expect the real first-year number, premium plus the training the policy forces you to buy, to land somewhere between about $6,000 and $25,000 as of 2025–2026. The bottom of that range is an instrument-rated pilot with 1,000 hours and some retract time buying a $150,000 Arrow. The top is a 300-hour VFR pilot buying a $400,000 turbocharged six-seater and paying for an instrument rating and a simulator course to get written at all.
Why Underwriters Balk at These Airplanes Specifically
Start with what the FAA actually requires, because it is far less than your insurer wants. Under 14 CFR 61.31(e), a complex airplane — retractable gear, flaps and a controllable-pitch propeller — needs ground and flight training plus a one-time logbook endorsement. Under 61.31(f), a high-performance airplane — more than 200 horsepower — needs the same. Neither rule sets a minimum number of hours. A sharp instructor can sign you off in an afternoon and you are legal for life.
The underwriter is not reading the FARs. They are reading loss runs. Retractable singles generate a steady stream of gear-related claims that are survivable, embarrassing and expensive, and the airplanes that carry retractable gear also tend to be faster, heavier and flown farther into weather than a fixed-gear trainer. A 180-knot airplane with a 60-gallon tank goes places a 110-knot airplane does not, which means night, ice, mountains and marginal VFR enter the risk picture whether you planned on them or not.
There is also a supply problem. Industry sources put the number of underwriters writing the bulk of U.S. general aviation piston business in the low double digits, and only a handful of those will seriously consider a low-time owner in a high-value retract. When two or three markets decline, your broker is not shopping a hundred companies — they are nearly out of doors to knock on.
Why It Matters: Insurance pilot requirements are contractual and separate from FAA pilot qualifications. Flying without meeting a policy's named-pilot, experience or training conditions can jeopardize coverage, even when the flight otherwise complies with FAA regulations. However, whether an insurer can deny a claim depends on the policy language, the circumstances and applicable state law. Pilots must also independently meet FAA requirements, including applicable flight-review and instrument-currency rules.
It helps to think of it the way a car insurer thinks about a 17-year-old. Nothing about you personally is reckless. You simply sit inside a group whose claim history sets the price, and the only way out of the group is time and documented training.
The Premium Itself: What Low Time Actually Costs
A piston single policy has two parts. Liability is usually a few hundred dollars and does not move much with your experience. Hull is quoted as a percentage of the agreed value you declare, and that percentage is where your logbook shows up.
As of 2025, brokers and owners report hull rates on retractable singles running roughly 1.2% to 2.5% of agreed value for a pilot who meets the market's comfort zone — instrument-rated, four figures of total time, real retract experience. The same airplane with a low-time VFR pilot is commonly quoted at 3% to 5%, when it is quoted at all. Run the math and the spread is brutal:
- A $150,000 Piper Arrow or Beech Sierra, 1,200-hour instrument-rated owner: roughly $2,200 to $4,000 a year all-in.
- The same airplane, 250-hour private pilot with no retract time: roughly $4,500 to $9,000, often with a 25-hour dual requirement attached.
- A $300,000-plus high-performance retract — A36 Bonanza, Cessna 210, turbocharged Mooney — with a qualified pilot: roughly $4,500 to $8,000.
- That same airplane with a low-time owner: $8,000 to $18,000 if a market will write it, and a real chance that none will.
Notice what the fixed-gear exception does. A Cirrus SR22 is high performance at 310 horsepower but has no gear to forget, and the factory training pipeline is standardized enough that underwriters price new owners far more gently than they would in a comparable retract. If you are weighing the two philosophies, our side-by-side on the Diamond DA50 and Cirrus SR22 and on the Piper M350 versus the SR22T both touch on how differently those airplanes insure.
One more variable that surprises people: the market cycle itself. The hard market that ran from roughly 2019 through 2022 pushed piston rates up year after year regardless of who you were. Brokers reported that pricing flattened and in some cases eased slightly for clean risks through 2024 and 2025 as capacity returned. We walk through those forces in why your aircraft insurance premium went up.
Flying411 keeps retractable and high-performance singles from every major manufacturer in one place, so you can compare asking prices before you ask a broker what each one costs to insure.
Transition and Dual Time: The Hours Written Into Your Policy
This is the cost most first-time buyers never budget for. When an underwriter agrees to write a pilot who is light on experience, the quote comes with conditions printed into the policy: a set number of hours of dual instruction in make and model before solo, sometimes a further block before carrying passengers, and often a requirement that the instructor meet the same minimums as the open pilot warranty.
Typical requirements for a retractable single as of 2025 look like this:
| Airplane | Total time usually wanted | Retract / make-and-model | Other conditions |
| 200 hp complex single (Arrow, Sierra, M20J) | 250–500 hours | 10–25 retract, 5–15 in type | Dual required before solo; instrument rating helps but is rarely mandatory |
| 285–310 hp retract (A36, C210, Mooney Bravo) | 500–1,000 hours | 50–100 retract, 15–25 in type | Instrument rating commonly required or heavily credited |
| Turbocharged or pressurized single | 1,000+ hours | 100+ retract plus turbo time | Instrument rating required; annual recurrent or simulator training required |
| High-performance fixed gear (SR22, DA50) | 150–500 hours | Factory or CSIP transition course | Standardized syllabus often substitutes for raw hours |
What does that dual cost? Instruction in your own airplane runs roughly $60 to $100 an hour for the CFI as of 2025, more for a specialist who travels to you. Add the operating cost of the airplane — fuel, oil and reserves on a 300 hp single realistically run $90 to $150 an hour — and a 25-hour requirement is a $4,000 to $6,000 line item before you have gone anywhere useful. A 10-hour requirement in a 200 hp complex single is closer to $1,500 to $2,500.
Pro Tip: Get the dual-hour requirement in writing before you close on the airplane, not after. Some buyers discover their quote assumed 10 hours and the bound policy says 25, which can mean the ferry flight home has to be flown by someone else.
There is a quiet benefit here. Those hours are the fastest way to retire the very experience gap the underwriter priced. Finish 25 hours in type and at next renewal you are no longer a stranger to the model — you are a named pilot with time in type and a clean year, which is exactly the profile that gets re-rated down.
The Instrument Rating: The Biggest Single Lever
If you want one purchase that moves the number more than any other, it is the instrument rating. For high-performance retracts, many markets treat it as a gate rather than a discount — no rating, no quote. Where it is optional, brokers commonly describe the credit as being in the 10% to 20% range, and it also tends to unlock better liability limits and lower in-motion deductibles.
Budget $9,000 to $18,000 for an instrument rating as of 2025, depending on whether you fly a rental, your own airplane, or a mix of simulator and aircraft time. Doing it in the airplane you just bought is more expensive per hour but kills two birds: the required dual in make and model and the rating itself can overlap substantially, and some underwriters will count instrument training time toward the transition requirement if the instructor qualifies.
Good to Know: The rating alone is not the whole story. Underwriters increasingly ask about instrument currency and recency, not just the certificate. A rating earned in 2009 with no approaches since reads differently on an application than a rating plus a current instrument proficiency check.
For pilots who are also eyeing a career path, the economics of stacking ratings while you own an airplane are worth thinking through — our piece on commercial certificate hours and costs covers how the hour requirements actually line up.
Recurrent and Type-Club Training: The Annual Spend That Pays Back
Once you have the airplane, the recurring training you choose is the part of the premium you can still control each year. Three tiers exist, and they are priced very differently.
Type-club clinics. The American Bonanza Society's Beechcraft Pilot Proficiency Program, the Mooney owners' proficiency programs run through MAPA, the Cirrus Owners and Pilots Association's CPPP, and the Cessna Pilots Association's type courses all follow the same model: a weekend of model-specific ground school plus three or four hours of flight in your own airplane with an instructor who knows that type's quirks. Figure $1,000 to $2,000 for the clinic, plus your own fuel and travel. Underwriters know these programs by name, and attendance is one of the easiest things for a broker to put in front of a reluctant market.
Simulator training. Dedicated piston-single simulator courses exist for the popular high-performance types. Owners report initial courses running roughly $3,000 to $6,000 and recurrent sessions roughly $1,500 to $3,500, depending on the model and the length of the course. For turbocharged and pressurized singles, annual simulator training is frequently a policy requirement rather than a choice — that is the deal you make for flying in the flight levels behind one engine.
Instructor time at home. The cheapest tier is an annual IPC and a thorough flight review with a CFI who actually knows the airplane, which runs $400 to $900 in instructor fees plus your operating cost. It buys the least credit, but it buys something, and it is the floor you should never drop below.
Keep in Mind: Some insurers recognize recurrent training and type-specific proficiency programs when evaluating a pilot's risk, but any premium discount varies by carrier and policy. The stronger reason to invest in recurrent training is improved proficiency, especially in emergency procedures and aircraft-specific operations. Ask your broker whether a particular course qualifies for a discount or helps satisfy a policy requirement before enrolling.
Flying411 keeps listings, specs and ownership guides for the same model side by side, so you can see what a type club exists for before you buy into the type.
Deductibles, Sublimits and the Hull Value You Declare
Two owners can pay the same premium and have very different policies. The levers nobody reads until the claim are the deductibles and the liability structure.
Deductibles on piston singles typically run $0 to $1,000 for not-in-motion damage and $1,000 to $5,000 in motion for an experienced pilot. Low-time pilots in retracts are often quoted in-motion deductibles of $2,500 to $10,000, and some quotes express it as a percentage — 5% or even 10% of the hull value — which on a $300,000 airplane means you are carrying the first $15,000 to $30,000 of a gear-up yourself. Raising a deductible voluntarily will shave the premium, but understand the number you are agreeing to eat.
Liability limits are where piston owners get a false sense of security. Most piston policies are written at a $1,000,000 combined single limit with a per-passenger sublimit of $100,000. If you routinely carry three or four people, that sublimit is the real limit. Smooth $1,000,000 — no per-passenger cap — is available from some markets for experienced, instrument-rated pilots and is one more thing low time quietly costs you.
Hull value is yours to declare, within reason, and on an agreed-value policy it is what you get paid. Insuring the airplane for less than it is worth lowers the premium proportionally and is a reasonable move on an older, lower-value airframe where a serious repair would total it anyway. It is a bad move on a freshly upgraded airplane where you would be paying out of pocket to rebuild what you just bought.
Heads Up: Avionics upgrades raise the replacement value of the airplane but do not automatically raise your hull coverage. If you put $35,000 of new panel into a $160,000 Bonanza, call your broker the week it comes out of the shop.
Key Takeaways
The refusal is almost never about you — it is about a claim profile that averages tens of thousands of dollars per event, written by a market with fewer than a dozen serious players. As of 2025–2026, an instrument-rated pilot with four figures of total time and real retract experience pays roughly 1.2% to 2.5% of hull value and lands in the $2,200 to $8,000 range depending on the airplane. The same airplane with a 250-hour VFR pilot is 3% to 5% if anyone writes it, and the gap between those two states is bridged by about $9,000 to $18,000 for an instrument rating, $1,500 to $6,000 of required dual in make and model, and $1,000 to $3,500 a year of recurrent or type-club training. Additional flight experience, an instrument rating, model-specific training and a clean claims history can improve a pilot's insurance eligibility and may lower premiums over subsequent renewals. However, the amount of any reduction depends on the aircraft, insurer, coverage limits, deductible and prevailing insurance market conditions. There is no reliable percentage reduction that applies to every owner.
| Cost | Low | High | Fixed, annual or per hour |
| Annual premium, $150k complex single, qualified pilot | $2,200 | $4,000 | Fixed annual |
| Annual premium, $150k complex single, low-time pilot | $4,500 | $9,000 | Fixed annual |
| Annual premium, $300k+ high-performance retract, qualified pilot | $4,500 | $8,000 | Fixed annual |
| Annual premium, $300k+ retract, low-time pilot (if written) | $8,000 | $18,000 | Fixed annual |
| Required dual in make and model (10–25 hr), CFI fee | $60 | $100 | Per flight hour |
| Aircraft operating cost during that dual | $90 | $150 | Per flight hour |
| Instrument rating | $9,000 | $18,000 | One-time |
| Type-club proficiency clinic (BPPP, MAPA, CPPP, CPA) | $1,000 | $2,000 | Annual, plus your fuel |
| Simulator course, initial | $3,000 | $6,000 | One-time |
| Simulator course, recurrent | $1,500 | $3,500 | Annual |
| Annual IPC plus flight review, instructor fees | $400 | $900 | Annual |
| In-motion deductible you carry | $1,000 | $30,000 (10% of hull) | Per claim |
| Gear-up repair exposure, prop strike teardown included | $30,000 | $80,000 | Per event |
Ways to Spend Less
Buy the 200 hp complex airplane first. An Arrow, a Beech Sierra or an M20J is complex but not high performance under 61.31(f), and the hull values are low enough that underwriters relax considerably. Two years and 150 hours in one makes the Bonanza quote a different conversation. What it trades away is speed and useful load now, and a second set of transaction costs later when you move up. Our comparison of the Beech Sierra and the Piper Arrow II is a reasonable place to start, and the Cessna 210 versus A36 Bonanza piece shows what the step up really buys.
Declare a realistic hull value, not an aspirational one. Insuring a $140,000 airplane for $175,000 "because prices are rising" costs you 1.2% to 5% of the difference every single year and pays you nothing extra on a partial claim. The trade: if values do run up and the airplane is destroyed, you are short.
Raise the not-in-motion deductible, leave the in-motion one alone. Hangar rash and ground handling claims are small and frequent; taking a $1,000 deductible instead of $250 shaves premium with limited downside. Doing the same on the in-motion side is how a gear-up turns into a $20,000 personal expense.
Go to the type club clinic every year, and send the certificate to your broker. This is the highest-return training dollar in the business — about $1,500 all-in for a weekend that buys a 5% to 15% credit, better market access, and a genuinely lower chance of the claim itself. The trade is a weekend and the fuel to get there.
Keep the same carrier. Loyalty is worth real money in a small market. Underwriters price renewals partly on the relationship, and a pilot who has been with one company through a rating, a clinic and three clean years gets treated better than the same pilot shopping annually. The trade: you may leave a few hundred dollars on the table in a soft year.
Consider a partnership. Two or three owners on one policy spread the fixed premium, and if one partner is a high-time instrument-rated pilot, the whole policy often reads better. The trade is scheduling, and the hard truth that a partner's claim is your claim at renewal.
Quick Tip: Ask your broker specifically whether the quote improves if you add a named-pilot requirement instead of an open pilot warranty. Restricting who may fly the airplane to you and one named instructor sometimes buys a meaningful reduction — useful if nobody else was going to fly it anyway.
Flying411 keeps ownership and cost guides alongside the listings, so you can compare what an airplane sells for against what it costs to keep insured and current.
Building the Profile an Underwriter Will Write
The practical path is boring and it works: get the instrument rating, log 50 to 100 hours of real retractable time in something modest, fly a type-specific clinic in the first year you own the airplane, and renew with the same carrier without a claim. Following those steps can make a high-performance retractable aircraft more attractive to insurers over time and may open additional coverage options. Premium reductions are possible, but they are not guaranteed, and insurers will continue evaluating the aircraft, pilot qualifications, claims history and market conditions at each renewal.
What does not work is arguing. Brokers are not gatekeepers you can talk around; they are shopping a short list of markets against a rate sheet. Give them something new to put in the submission — a rating, a certificate, hours in type — and they can go back. Give them the same application twice and they will get the same answer. That is the whole mechanism behind insurance for a retractable or high-performance single, and once you see it that way, the money you spend on training stops feeling like a tax and starts looking like the cheapest part of the airplane.
When you are ready to compare listings, visitFlying411and see what is on the market today.
Frequently Asked Questions
How many hours do I need before an underwriter will insure me in a Bonanza or a 210?
There is no universal number, but as of 2025 most markets want to see roughly 500 to 1,000 total hours, 50 to 100 hours of retractable time and an instrument rating before a 285–310 hp retract is comfortable. Below that, expect either a decline, a high rate with a large in-motion deductible, or a quote conditioned on 15 to 25 hours of dual in make and model before you fly it alone.
Does the FAA high-performance endorsement satisfy my insurance company?
No. The 61.31(f) endorsement makes you legal and has no minimum hour requirement. Your policy's pilot warranty is a separate contract with its own numbers, and flying outside it can void coverage even though the flight is perfectly legal. Always read the pilot clause in the bound policy, not just the quote.
Will an instrument rating really lower my premium?
On a high-performance retract, yes — brokers commonly describe credits in the 10% to 20% range, and on turbocharged or pressurized singles the rating is often required outright. On a low-value fixed-gear airplane the credit is smaller. The rating also tends to unlock smooth liability limits and lower deductibles, which are worth more than the headline discount.
Is simulator training worth it for a piston single?
It depends on the airplane. For a 200 hp complex single, a type-club clinic at $1,000 to $2,000 gives you most of the benefit for a fraction of the cost. For turbocharged, pressurized or high-value singles, annual simulator training at $1,500 to $3,500 recurrent is frequently a policy condition, and the emergency scenarios you can practice in a box are ones you would never fly in the airplane.
What happens to my premium after a gear-up landing?
Expect a significant increase at the next renewal, a higher in-motion deductible, and in some cases non-renewal that sends you shopping a market that already knows about the claim. A gear-up is a survivable event with an outsized financial tail, which is exactly why underwriters price newcomers to retractable gear the way they do.